GENERAL
To choose freight insurance that fits your business, start with three questions: what are you shipping, how and where does it travel, and how often do you ship? With Australia’s diverse geography and complex trade relationships, the right cover can mean the difference between a minor inconvenience and a business-threatening loss.
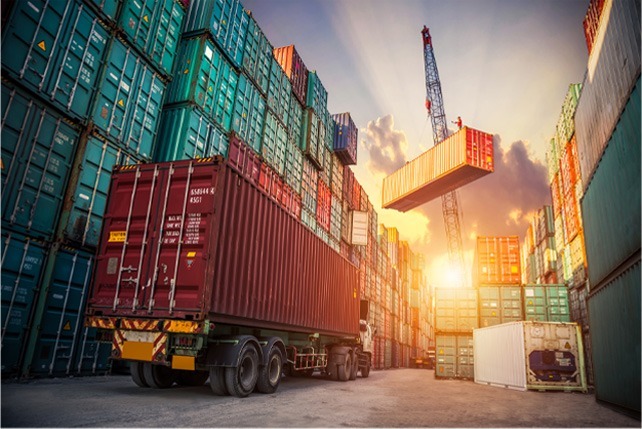
What types of freight insurance cover are there?
Transit insurance for domestic shipments
Domestic cargo and transit insurance can cover goods moving within Australia by road, rail or air, subject to the policy terms, conditions and exclusions. It matters for businesses moving cargo across Australia’s vast distances, where risks include vehicle accidents, theft and weather events.
Marine insurance for international trade
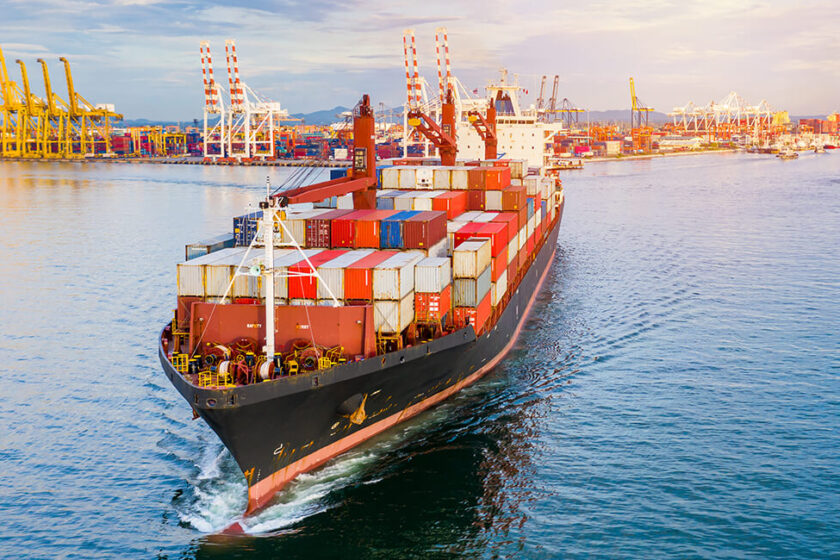
Marine cargo insurance protects goods during sea freight and, depending on the policy, can extend to loading, unloading and temporary storage. It is important for importers and exporters, because the ICC Incoterms rules in your sales contract decide when risk passes from seller to buyer.
Which cargo may need specialised cover?
- high-value technology and electronics
- temperature-sensitive pharmaceuticals and food products
- dangerous goods requiring specialised handling
- agricultural products with unique storage requirements
What should Australian businesses consider when choosing freight insurance?
What are you shipping?
The nature of your goods determines your cover requirements. High-value electronics need different protection from bulk agricultural products. Consider the replacement cost, not just the original purchase price.
How and where does it travel?
Long-distance road transport faces different risks from short-haul rail or coastal shipping. International routes add complexity through customs, handling and political risks.
How often do you ship?
Regular shippers often benefit from annual transit insurance, which covers shipments over a 12-month period with simpler administration. Occasional shippers may prefer single-trip cover for specific high-value shipments.
What common mistakes should you avoid?
- Under-insuring cargo value: insuring goods at cost price rather than replacement value can leave significant gaps at claim time. Declare the full replacement value, including freight costs.
- Relying on carrier liability alone: standard carrier liability is often limited and can leave substantial exposure on high-value shipments. See our carriers liability FAQs.
- Ignoring policy exclusions: common exclusions include improper packaging, inherent vice and delay, and some policies also exclude or limit certain weather events. Understanding them helps you avoid disappointment at claim time.
- Inadequate documentation: poor record-keeping can delay or prevent claims. Keep detailed packing lists, photos and handling instructions for every shipment.
How can a broker help you choose?
The right freight insurance strategy balances comprehensive protection with cost-effectiveness. An experienced broker understands Australian trade patterns and can negotiate terms with multiple insurers. Freight Insurance Services International (FIS International) is an Australian insurance broker based in Moorabbin, Melbourne. Learn more about our team or call 1800 656 836.
Frequently Asked Questions
Can one policy cover both domestic and international shipments?
Yes. Annual transit insurance can cover your domestic, import and export shipments under one policy, so you do not need separate arrangements for each type of trade.
Can I switch from single transit policies to annual cover?
Yes. An annual policy can start at any time, and from then on your eligible shipments are covered under it. Any single transit policies you have already bought continue until those journeys end.
Is there a minimum business size for freight insurance?
No. A small business shipping occasionally can buy single transit cover online in minutes, while businesses that ship regularly usually save time and money with an annual policy.
This information is general in nature and does not take into account your objectives, financial situation or needs. Please read the policy wording and our Financial Services Guide before deciding.